Tata Motors Passenger Vehicles Swings to ₹5,531 Crore Loss as Raw Material Costs Surge
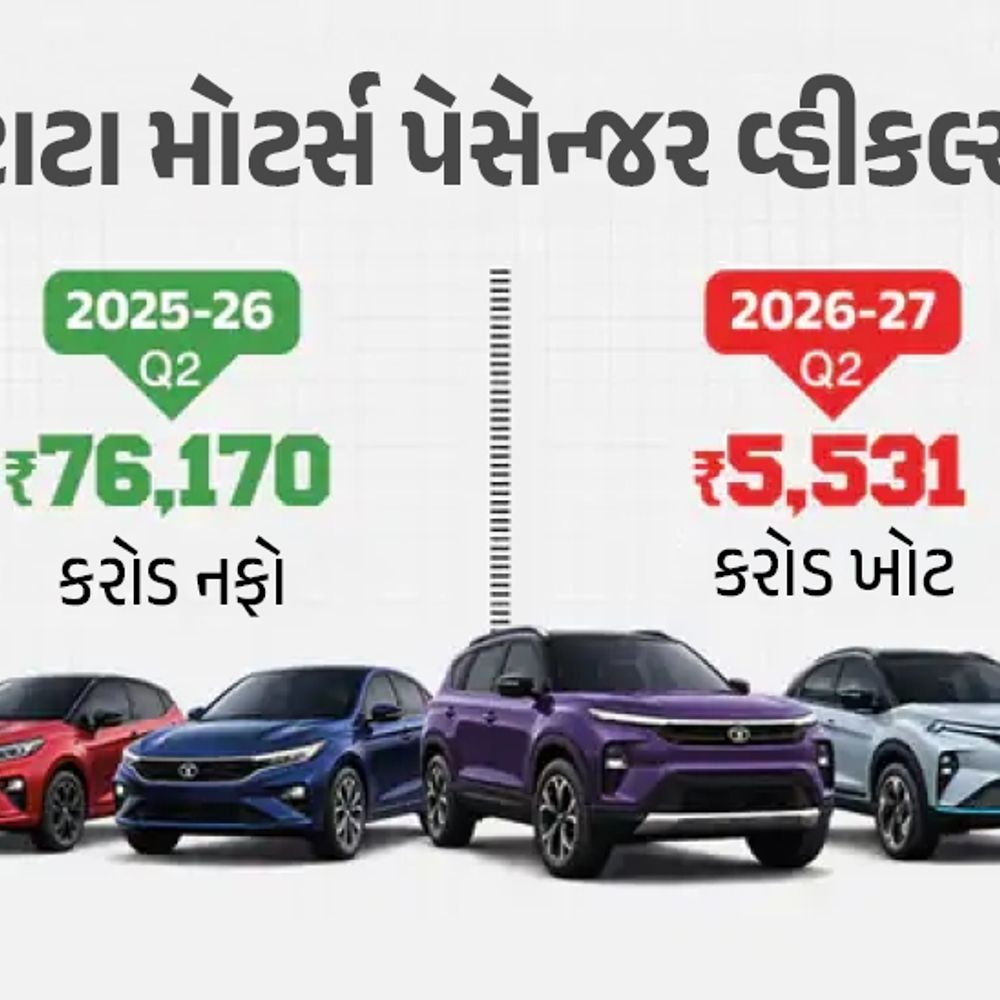
Tata Motors Passenger Vehicles reported a net loss of ₹5,531 crore for the second quarter, reversing a ₹76,170 crore profit from the previous year as surging raw material expenses severely squeezed operating margins.
In this piece
Tata Motors Passenger Vehicles recorded a net loss of ₹5,531 crore for the second quarter, sharply down from a ₹76,170 crore profit a year earlier. The…
Tata Motors Passenger Vehicles reported a consolidated net loss of 5,531 crore rupees for the second quarter, marking a sharp downturn from the substantial profitability recorded in the corresponding period of the previous year. The automotive manufacturer had posted a net profit of 76,170 crore rupees during the prior-year period, underscoring the severity of the financial contraction. According to preliminary financial reports, elevated raw material expenses emerged as the primary headwind depressing quarterly performance.
The swing into negative territory highlights severe cost pressures bearing down on vehicle manufacturing margins. While the company maintained production activity across its vehicle portfolio, escalating input costs substantially eroded operating profitability. The sharp contrast between the latest net loss and the prior year's multi-crore profit reflects significant operational volatility within the passenger automotive segment.
Rising costs for essential production materials, including automotive-grade metals, specialized components, and industrial inputs, have increasingly weighed on heavy manufacturers. Automobile producers have faced prolonged cost inflation throughout global and domestic supply networks over recent quarters. For passenger car makers, sustained increases in procurement pricing directly squeeze margins unless fully offset by retail price hikes or operational cost-reduction measures.
Automotive manufacturers frequently face difficult trade-offs when attempting to pass rising input expenses directly on to consumer retail prices. Aggressive price increases risk curbing showroom footfall and dampening consumer demand across competitive mass-market and mid-tier segments. As a consequence, vehicle producers often absorb a portion of procurement inflation, temporarily denting bottom-line returns to defend showroom volumes and brand market share.
The passenger vehicle sector has been navigating an evolving industry landscape characterized by changing regulatory requirements, technological upgrades, and macroeconomic shifts. In addition to material cost surges, vehicle makers must balance capital expenditures required for next-generation platform development, emission compliance, and expanding powertrain options. These concurrent capital commitments leave operating balance sheets more vulnerable to sudden margin compressions when supplier charges rise.
The steep financial reversal serves as a prominent indicator of the operating environment facing leading automotive players in the domestic passenger market. Institutional analysts and market participants closely monitor quarterly bottom-line figures to gauge corporate resilience against global supply chain cost shocks. Significant margin deterioration in a flagship passenger brand signals broader cost and pricing friction across the automotive component and assembly ecosystem.
For ancillary suppliers and parts manufacturers, quarterly earnings compressions among major original equipment manufacturers often trigger heightened cost audits and procurement negotiations. Automotive assemblers under profitability stress typically review supplier contracts, seeking efficiency gains and extended payment structures to contain outgoing cash flows. Consequently, persistent raw material pressures at the vehicle assembly level can ripple through tiered vendor networks across the wider automotive manufacturing chain.
In response to fluctuating input expenses, automobile manufacturers typically look toward strategic localization, component modularity, and value-engineering initiatives to restore financial equilibrium. Operational adjustments, including inventory optimization and tighter procurement oversight, serve as common counterweights against volatile commodity cycles. Sustained cost-management measures will be critical in determining how rapidly the company can rebound from the quarterly downturn.
Moving forward, industry observers will focus on whether easing commodity prices or upcoming production efficiencies provide relief in subsequent quarters. Market watchers are also awaiting detailed corporate disclosures regarding vehicle delivery volumes, model-specific margins, and ongoing mitigation plans. The trajectory of consumer purchasing activity and stabilizing component costs will likely dictate whether the passenger vehicle unit can quickly return to profitability.
Primary source: Divya Bhaskar Business. Newzly rewrites and structures source reporting for clarity; verify critical details at the original.