Bloom Energy Slides as Cash Flow Deficit Overshadows Record Q3 Revenue
Bloom Energy shares dropped sharply on Friday as investors looked past record third-quarter revenue to focus on heavy capital expenditure and persistent negative cash flow from rapid expansion.
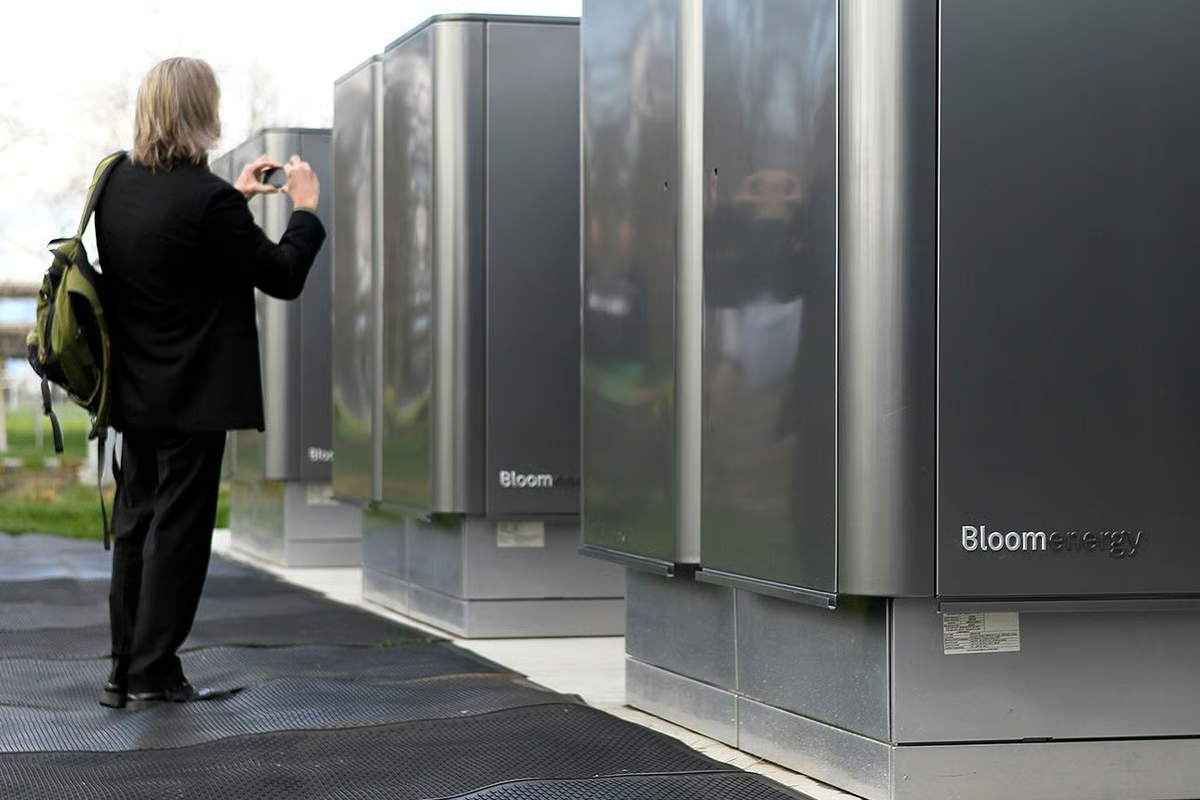
Shares of Bloom Energy fell sharply on Friday, reversing earlier momentum as Wall Street scrutinized the company's deteriorating cash position. Despite delivering a beat-and-raise performance highlighted by record quarterly revenue, the fuel-cell manufacturer faced aggressive selling pressure throughout the session. Investors reacted negatively to substantial operating cash outflows and elevated capital expenditures tied to rapid capacity expansion.
The market reaction stood in stark contrast to top-line headline results that initially appeared robust. Bloom Energy reported third-quarter revenue of 1.24 billion dollars, representing a 138 percent surge compared to the same period last year. Management also lifted its full-year guidance, pointing to strong commercial momentum and accelerating order volume.
The rapid revenue surge has been fueled primarily by intense electricity demand from artificial intelligence data centers and commercial customers. Power-hungry facilities have increasingly turned to solid oxide fuel-cell installations as grid congestion delays access to traditional utility connections. Bloom has capitalized on this structural bottleneck by marketing modular, on-site energy servers that can deploy faster than centralized power infrastructure.
Beneath the record sales figures, however, financial metrics revealed substantial strain on working capital and liquidity. Bloom Energy generated negative operating cash flow and recorded negative free cash flow of approximately 181 million dollars for the quarter. The widening deficit raised immediate concerns among market participants about the timing and sustainability of cash conversion as business volumes accelerate.
The cash drain stemmed largely from aggressive spending aimed at scaling production lines and fulfilling massive customer commitments. Bloom logged its highest-ever quarterly capital expenditures as it expanded factory footprints and poured funds into long-cycle customer assets. Substantial resources were also absorbed by rising inventories and extended accounts receivable, deferring the cash collection cycle.
The retreat in the share price was amplified by investor positioning and elevated market expectations leading into the announcement. Bloom Energy stock had experienced a sharp upward rally earlier in the year, leaving the company trading at a premium valuation. The earnings report provided a catalyst for institutional funds to lock in profits while awaiting clarity on balance sheet health.
The divergence between top-line expansion and liquidity reflects broader structural hurdles confronting the clean technology manufacturing sector. Scaling specialized hardware to meet surging grid demand requires heavy upfront commitments of working capital well before revenues translate into realized collections. For Bloom, proving that heavy factory investments will yield durable positive cash flows has become a central test of investor confidence.
Analysts noted that while manufacturing capacity is expanding, prolonged negative operating cash flow could limit financial flexibility if order conversions stall. Sustaining high capital intensity during a period of market expansion leaves little margin for execution missteps or supply-chain bottlenecks. Market observers stressed that disciplined cash management will be vital to protecting shareholder equity against potential dilutive financing.
Looking ahead, attention will focus on Bloom Energy's ability to demonstrate operating leverage as recently expanded capacity comes fully online. Management faces the challenge of normalizing inventory build-ups, compressing collection cycles, and transitioning record top-line contracts into consistent cash generation. Until operating cash flow turns reliably positive, market sentiment is expected to remain sensitive to quarterly capital consumption.
Primary source: Yahoo Finance Markets. Newzly rewrites and structures source reporting for clarity; verify critical details at the original.